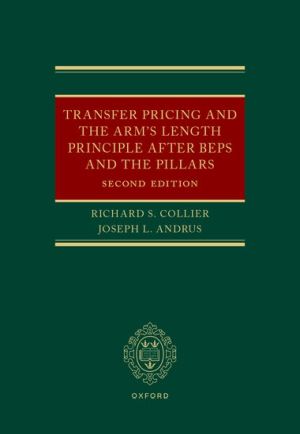
The first edition of this book presented the first sustained analysis and critique of arm's length-based transfer pricing following the OECD/G20 Base Erosion and Profit Shifting (BEPS) project. Since then, there has been a second major wave of international tax reform-the OECD/G20 Two Pillar project-with significant implications for transfer pricing and the future of the arm's length principle.
This thoroughly revised second edition examines the practical experience of implementing these recent reforms, assessing their implications for transfer pricing practice. It traces the development of the arm's length principle, analyses the operation of internationally accepted transfer pricing rules prior to the recent reform initiatives, and evaluates the challenges that have emerged in their wake.
The issues highlighted include problems relating to the complexity of the rules, the use and availability of comparables, and, in particular, problems permitting avoidance and income shifting (including problems related to low-tax entities with 'excessive capital'). The difficulties for the arm's length principle arising from the 'digitalization' of the economy, as well as new challenges created by the Two Pillar reform efforts, are also analysed.
Written by authors with deep practical experience of applying the transfer pricing rules, Transfer Pricing and the Arm's Length Principle After BEPS and the Pillars provides an authoritative and up-to-date assessment of one of the most topical and contested areas of international tax law.